Tag Archive for: banks

Trump Admin. Ramps Up Immigration Enforcement as Squeamish Republicans Are Left Behind

Despite volatile approval ratings and an on-again-off-again conflict with Iran, President Donald Trump is still working hard to deliver on his promise of restoring safety, security, and sovereignty to the American people by driving out the illegal immigrant population — and steamrolling those who try to stop him.

‘Restoring Integrity to America’s Financial System’

In an executive order issued Tuesday, the president imposed meaningful restrictions on illegal immigrants’ access to banks, cutting off a major incentive for foreigners seeking to violate U.S. immigration law. “America’s financial institutions serve a critical role in safeguarding the American people against financial fraud and abuse,” Trump observed in his executive order, “Restoring Integrity to America’s Financial System.” He continued, “My Administration will not tolerate national security and public safety risks caused by illicit cross-border financial activity, nor will it permit risks to our financial system posed by the extension of credit or financial services to the inadmissible and removable alien population.”

The president demanded that banks and other financial institutions enforce “know-your-customer” policies and verify the identity of clients attempting to open or manage accounts, including by requesting proof of U.S. citizenship or legal residence and work authorization. More than $310 billion has been laundered through U.S. financial institutions, the president noted, including money used for terrorist organizations, drug trafficking rings, and human trafficking operations.

“Banks and other financial institutions should also be attentive to the credit risks posed by the extension of mortgage and auto loans, credit cards, and other consumer credit to the inadmissible and removable alien population,” Trump continued. He pointed out that illegal immigrants face a heightened risk of loss of wages, either when they are arrested and deported by the federal government or when their employer decides to comply with federal immigration law and not hire illegal immigrants. “Lending to aliens without legal work authorization or who face a substantial loss-of-wage risk creates a structural ‘ability to repay’ deficiency that undermines the safety and soundness of the national banking system,” the president wrote. “Additionally, employers who violate immigration law may underreport wages, use mismatched or invalid Social Security numbers and taxpayer identification numbers, or fail to properly withhold or remit payroll taxes,” he added. “Such schemes can create vulnerabilities within our financial system by obscuring income sources, distorting credit underwriting, and facilitating underground economic activity.”

The executive order instructs Treasury Secretary Scott Bessent to analyze measures already in place to prevent illegal immigrants from opening and operating bank accounts and identify weaknesses in current regulations, adjusting the Bank Secrecy Act as necessary “to strengthen risk-based customer due diligence requirements for covered financial institutions.” The order will also require the Consumer Financial Protection Bureau (CFPB) to advise credit institutions that “potential deportation and loss of wages are factors that could adversely affect a non-work authorized borrower’s ability to repay an extension of credit under the ‘ability-to-repay’ standards” of 12 CFR Part 1026, commonly known as Regulation Z, which is aimed at protecting consumers in consumer credit transactions by barring abusive practices and standardizing how costs are disclosed.

George Fishman, senior legal fellow at the Center for Immigration Studies and a former lawyer for the Department of Homeland Security (DHS), noted that Trump’s executive order aims to correct more than two decades of the Treasury Department’s failure to block illegal immigrants from using U.S. financial institutions and prolonging their illicit stays in the country. While the 2001 Uniting and Strengthening America by Providing Appropriate Tools Required to Intercept and Obstruct Terrorism (USA PATRIOT) Act ordered the Treasury to “require financial institutions to implement … reasonable procedures for … verifying the identity of any person seeking to open” a bank account in order to “provide the United States government with new tools to combat the financing of terrorism and other financial crimes.”

“But the regulations that the Treasury actually wrote turned Congress’s intent on its head,” Fishman observed. Notably, the Treasury Department recommended that financial institutions accept Mexican consular registration cards, used by Mexican nationals as a form of identification, instead of requiring proof of U.S. citizenship or legal residence or work authorization. “Why?” Fishman asked. The Treasury Department said at the time it was trying “to find a balance between the need for strong regulation that provides a real benefit to those working to achieve national security and law enforcement objectives and the ability of financial institutions to serve non-U.S. persons,” worrying that “efforts to deter money laundering and disrupt terrorist financing … might have a negative impact on … encourage[ing] … non-U.S. persons living and working in the United States [read: illegal aliens] to use mainstream financial services.”

“I am sorry that ‘efforts to deter money laundering and disrupt terrorist financing’ might have interfered with encouraging illegal aliens to use our banking system!” Fishman wrote. “These were not words written by President Obama’s Treasury — they were written by the Treasury of President George W. Bush, on whose watch the 9/11 terrorist attacks had occurred not long before,” he added. “June 9 will be the 23rd anniversary of the effective date of Treasury’s permissive regulations. President Trump has given us hope that those regulations will not see another one.”

Toe the Immigration Hardline

Immigration was a core Trump campaign issue in 2024, and the president has not favored Republicans who refuse to support his immigration agenda. Notably, Rep. Thomas Massie (R-Ky.) was defeated in a contentious, high-profile primary challenge earlier this week, after Trump called for the congressman to be ousted. Last year, Massie was the only Republican in the U.S. House of Representatives to oppose the One Big Beautiful Bill, which provided funding for DHS components, including Immigration and Customs Enforcement (ICE) and critical border security provisions. Trump responded by labeling Massie “just another GRANDSTANDER, who’s too much trouble, and not worth the fight,” and succeeded in ending his congressional career.

According to Numbers USA, Massie has only voted in favor of immigration restriction and border security provisions 57% of the time over the course of his nearly-15 years in Congress, earning a “C+” rating, one of the lowest among Republicans. More than 200 Republican legislators earned a higher score than Massie on immigration reduction and border security.

Massie wasn’t the only Republican ousted for refusing to cooperate with the president on immigration. In Alabama’s Lee County, 30-year Sheriff Jay Jones (R) was voted out of office, to be succeeded by Cameron Hunt (R), a former sheriff’s deputy. Jones had publicly refused to cooperate with ICE in immigration enforcement, a point which Hunt brought up in campaigning against his former boss. “Let me be clear. This is a failure of leadership,” Hunt said of Jones’s refusal to participate in the 287(g) program, which allows ICE to deputize local law enforcement authorities to assist in immigration enforcement. “Had that program been in place here, there is a very real possibility this violent offender would have already been off the streets,” Hunt continued, referring to an incident in which a sheriff’s deputy was shot while attempting to arrest a Guatemalan national wanted for first-degree rape. “Lee County is one of the fastest-growing counties in Alabama. Growth without a proactive public safety strategy is a risk we cannot afford.” Lee County’s voters clearly agreed. Hunt has pledged to sign onto the 287(g) program.

Congresswoman Takes on Foreign-Born Congressmen

While not a member of Trump’s administration, Rep. Nancy Mace (R-S.C.) introduced a proposal Wednesday to amend the Constitution to bar those born in foreign countries from serving in Congress, the federal judiciary, or as Senate-confirmed officers in the executive branch. “If you hold power in the American government, you should be a natural born American citizen,” Mace said in a statement. “This is not complicated. The people writing America’s laws, confirming America’s judges, and representing America on the world stage should have one loyalty: America. Not Somalia. Not any other country,” she continued. “For too long we have allowed foreign born members to hold seats in this government while making clear their loyalty is not here. We see it every day. This amendment puts an end to it.”

In a separate social media post touting the proposed amendment, Mace noted that the president and vice president are already constitutionally required to be born in the U.S. to hold office. She also pointed out that some of the most left-wing members of Congress — namely Reps. Ilhan Omar (D-Minn.), Pramila Jayapal (D-Wash.), and Shri Thanedar (D-Mich.) — were all “born in foreign countries, none were citizens by birth. All sitting in the United States Congress. All making clear every single day their loyalty is not to America.”

Of the 26 U.S. House representatives and six senators born in foreign countries, 24 are Democrats, while 19 were born outside the U.S. not to American citizens.

AUTHOR

S.A. McCarthy

S.A. McCarthy serves as a news writer at The Washington Stand.

RELATED ARTICLES:

Trump Admin Closes Loophole Letting Migrants Stay In U.S. While Awaiting Green Cards

Democrats Publish Long-Awaited 2024 Campaign ‘Autopsy’

EDITORS NOTE: This Washington Stand column is republished with permission. All rights reserved. ©2026 Family Research Council.


The Washington Stand is Family Research Council’s outlet for news and commentary from a biblical worldview. The Washington Stand is based in Washington, D.C. and is published by FRC, whose mission is to advance faith, family, and freedom in public policy and the culture from a biblical worldview. We invite you to stand with us by partnering with FRC.
Half of America’s Banks Are Potentially Insolvent

Thousands of banks are underwater. Another Biden spectacular.

Watch the Democrat media axis package this steaming pile of dung as a marvelous, transformative moment.

Half of America’s banks are potentially insolvent – this is how a credit crunch begins

By: Ambrose Evans-Pritchard, Yahoo Finance, May 2, 2023:

The twin crashes in US commercial real estate and the US bond market have collided with $9 trillion uninsured deposits in the American banking system. Such deposits can vanish in an afternoon in the cyber age.

The second and third biggest bank failures in US history have followed in quick succession. The US Treasury and Federal Reserve would like us to believe that they are “idiosyncratic”. That is a dangerous evasion.

Almost half of America’s 4,800 banks are already burning through their capital buffers. They may not have to mark all losses to market under US accounting rules but that does not make them solvent. Somebody will take those losses.

“It’s spooky. Thousands of banks are underwater,” said Professor Amit Seru, a banking expert at Stanford University. “Let’s not pretend that this is just about Silicon Valley Bank and First Republic. A lot of the US banking system is potentially insolvent.”

The full shock of monetary tightening by the Fed has yet to hit. A great edifice of debt faces a refinancing cliff-edge over the next six quarters. Only then will we learn whether the US financial system can safely deflate the excess leverage induced by extreme monetary stimulus during the pandemic.

A Hoover Institution report by Prof Seru and a group of banking experts calculates that more than 2,315 US banks are currently sitting on assets worth less than their liabilities. The market value of their loan portfolios is $2 trillion lower than the stated book value.

Keep reading.


AUTHOR

RELATED ARTICLE: Biden Regime Cracks Down on Dishwashers as War on Appliances Continues

RELATED TWEET:

EDITORS NOTE: This Geller Report is republished with permission. ©All rights reserved.

ALERT: Banks Exiting the FHA Refinance Market

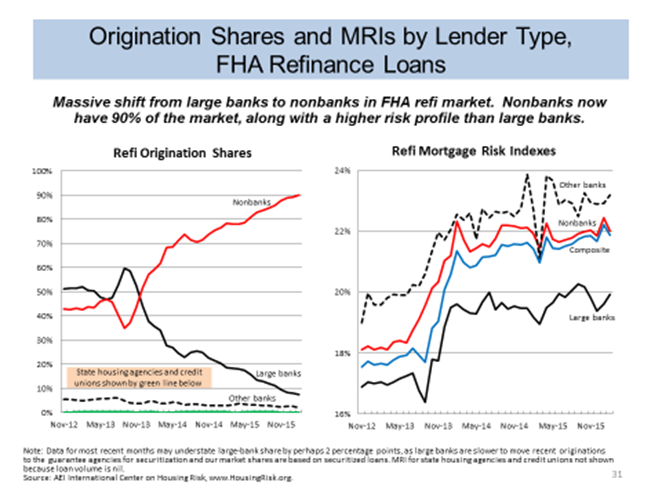
The below chart (left panel) shows a shift away from both large and other banks that dwarfs even what has happened with share shift for lender FHA purchase loan share. Said another way, banks in general have largely exited the FHA refinance market, with non-banks accounting for 90% share in February.

image1

This is a continuation of the three plus year trend of bank withdrawal from FHA lending, a market they dominated just 3-4 years ago.

Contributing to this shift are concerns over:

  • Regulatory risk and legal liability
  • Reputational risk
  • Servicing costs
  • Customer relationships
  • FHA’s extremely high risk profile (right panel above)

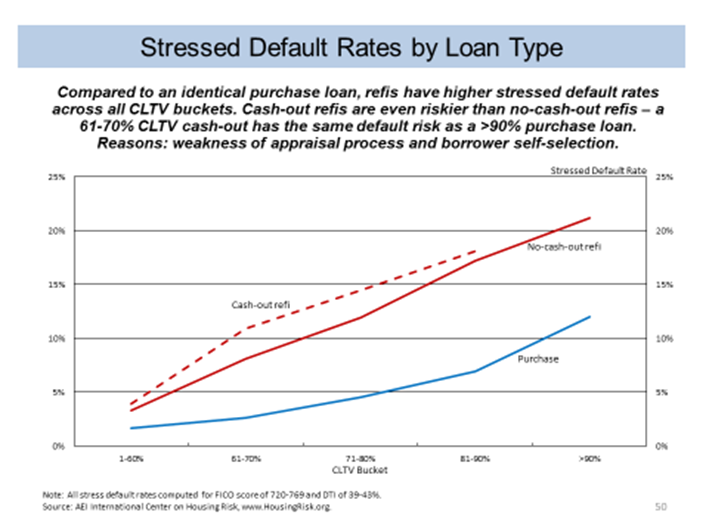
The shift away from banks to non-banks has important ramifications, as non-banks are much more willing to originate high risk loans. As the chart below demonstrates, refinance loans are much riskier than purchase loans with the same characteristics and non-banks now control 90% of FHA finance securitizations using Ginnie Mae:

image2

To view the entire National Housing Risk Index and other Risk Measures briefing click here.

Study shows seismic shift in lending away from large banks to non-banks

Study shows seismic shift in lending away from large banks to non-banks continued in February By Stephen D. Oliner, Edward J. Pinto and Brian C. Marein.

A new study released by the AEI International Center on Housing Risk found that the seismic shift in home purchase loan originations away from large banks to non-banks continued in February.  Since November 2012, the large bank share has dropped from 61 percent to 33 percent (see the report below).  The share shift was unabated in February as the large bank share dropped 1.2 percentage points from  previous month.  The dramatic decline in the large bank lending share has been met point-for-point by an increase in the non-bank share, which has risen from 24 percent to 51 percent.  Large non-banks and other non-banks each have accounted for about half of the 27 point increase in share.

This shift is due to the fact that non-banks compared to large banks are more thinly capitalized and more lightly regulated, generally face less reputational and litigation risk, and tend to have a shorter term outlook. Additionally, their primary business is generally just mortgage banking as compared to the more diversified business lines of large banks.  Therefore they have a more limited ability to stay on the sidelines.

Key Takeaways:

  • The dramatic decline in agency market share for large banks continued unabated in February, offset by an equally dramatic increase in the non-bank share.
  • Since November 2012, the large bank share has dropped from 61% to 33%, a move of 28 points, including a 1.2 point drop in February, a dramatic decline that has been met point-for-point by a 27 point increase in the non-bank share from 24% to 51%. Large non-banks and other non-banks have participated equally in the increase, accounting for 14 points and 13 points respectively.
  • Large banks have reduced the riskiness of their agency mortgage originations over the past few years. Non-banks, in contrast, have shifted toward riskier loans as they have increased their market share.
  • Loans originated through the retail channel are less risky than loans originated through the broker and correspondent channels. This is true both for large banks and for non-banks. But retail channel loans from non-banks are substantially riskier than such loans from large banks.
  • The bottom line is that large banks attempting to regain market share would have to move well out the risk curve.

Sending Money Home: Technology or Bureaucracy? by Iain Murray

Remittances are helping poor people globally, but regulators loom.

Some of the world’s poorest people depend on the money they receive from relatives working in developed countries. In fact, this money dwarfs the world’s official foreign aid budget, and the gap is increasing.

In 2011, total private flows of aid totaled $680 billion—almost five times the $138 billion official figure. As I noted in 2005, “the future of aid to developing countries is private.”

This increase in private aid is great news for all concerned. Except, perhaps, for bureaucrats, who are loath to let good deeds go unpunished. World Bank and United Nations bean counters are denouncing remittance transfer fees as exploitative. The U.S. Consumer Financial Protection Bureau (CFPB) has issued a rule to crack down on supposed fraud and exploitation affecting the existing remittance-transfer infrastructure. Its most important provision is the right to cancel a money transfer within 30 minutes of its being initiated. Proposals to cap the fee charged by remittance firms have also been agreed to internationally.

Critics claim that high transfer fees are the result of a so-called market failure. Yet, markets in remittances are frequently overregulated. Many African governments have exclusive deals with money transfer companies, which operate as national monopolies, free from competitive discipline. And there are other regulatory pitfalls that drive up prices. A Western Union spokesman told The Guardian: 

Our pricing varies between countries depending on a number of factors, such as consumer protection costs, local remittance taxes, market distribution, regulatory structure, volume, currency volatility and other market efficiencies. These factors can impact the fees and foreign exchange rates offered by corridor and service type.

All this suggests the remittance market needs less regulation. Proper competition, lower taxes, less restrictive “consumer protection” measures (which quickly become outdated), and less red tape in general would all likely increase the flow of funds between individuals.

Such a solution would be inconceivable for global bureaucrats. Indeed, their house organ, The New York Times, last week recommended that the industry should be not only nationalized, but internationalized, with the World Bank taking on the role of remittance service provider, a role the Times actually described as “critical”:

The World Bank could pool deposits from banks and nonbank money transfer agents and parcel them to recipient banks, using its formidable certification protocols to verify that the money is coming from and going to legitimate parties. Such pooling could also reduce exchange fees, a big cost to migrants. Equally important, the World Bank could use its relationships with regulators around the world to enhance the remittance system’s integrity.

Technology is already solving many of the problems faced by the money transfer industry, making the industry obsolete in the process. For example, in the central Asian republic Kyrgyzstan, which relies heavily on remittances—accounting for 31 percent of its GDP, mostly from within the former Soviet Union—an Italian entrepreneur named Emanuele Costa is able to promote bitcoin as an alternative to the expensive, heavily regulated money transfer firms. 

Costa can do this because Kyrgyzstan is notably less oppressive and more free-market-oriented than its neighbors, and it has much less regulation than is typical in the area. He regularly hosts meetups to explain the currency to potential recipients and has installed a bitcoin ATM at a pizzeria (which, as Eurasianet notes, has been “bombarded with calls” since it publicized its existence).

In Kenya, meanwhile, a bitcoin startup called BitPesa offers money transfers “twice as fast and 75% cheaper” than traditional competitors. Kenya is an especially interesting place for this innovation to happen, as it was the scene of a “cell phone revolution” that allowed its telecommunications market to work around a serious case of government failure. As a result, most Kenyans now use a form of mobile wallet on their cell phones.

The potential for bitcoin to revolutionize the global remittance industry is hard to overstate. It largely cuts out the middleman, reducing the fees and charges some view as exploitative. Converting to local currency would be the most significant charge for most users. Bitcoin facilitates the establishment of trust through its “blockchain” public ledger, potentially reducing fraudulent transfers to near zero (although there is always the chance of someone stealing a wallet key). Taxes, at the moment, are minimal. 

For these reasons, bitcoin represents the best hope to ensure that all of the $680 billion in remittances goes to the people who need it. That might be why in America, bitcoin is most popular among Hispanics, who send more money abroad than any other group.

Yet, roadblocks remain. If Kyrgyzstan joins Moscow’s customs union as expected, bitcoin’s days may be numbered there, as Russian officials have taken a dim view of anonymous payment vehicles. Meanwhile, in the UK, where many Kenyan remittance senders live and work, banks are wary of taking bitcoin businesses on as clients. As BitPesa’s founder told The Guardian:

Most UK banks won’t let Bitcoin businesses open bank accounts. These businesses want to be licensed, but UK banks shy away, just like Barclays cut Somalia off the map. 

British banks are highly regulated and probably fearful of what regulators might do to them if they did business with companies that present “reputational risk”—as defined by regulators, of course.

In the United States, the CFPB rule mentioned above could threaten to make bitcoin illegal for remittance purposes. The average time for a Bitcoin transaction to go through is around eight minutes, and reversing a transaction is impossible unless an escrow service is used. It is possible that the rule may not apply to a decentralized network like bitcoin, but in its short existence, the CFPB has not become known for reading its powers narrowly.

Regulators could wind up killing off the solution to problems created by, well, regulators. If they are serious about reducing costs and decreasing the potential for fraud in remittances, they will stand aside and let bitcoin develop in this role. If the choice is between a distributed, autonomous cryptocurrency network approved by the people who need the remittances most, or a combination of policies approved by The New York Times, the World Bank, and international regulators, Public Choice economics suggests that the technological option faces a long struggle ahead.

ABOUT IAIN MURRAY

Iain Murray is vice president at the Competitive Enterprise Institute.

EDITORS NOTE: The featured image is courtesy of FEE and Shutterstock.

Are US banks enabling manipulation on a vast scale?

Geo Intelligence states, “Top economists, financial experts and bankers say that the big banks are too large … and their very size is threatening the [US] economy.”

On June 27, 2013 Representatives Alan Grayson (D-FL), Raul Grijalva (D-AZ), John Conyers (D-MI) and Keith Ellison (D-MN) sent a letter to Federal Reserve Chairman Ben Bernanke. The letter states, “We write in regards to the expansion of large banks into what had traditionally been non-financial commercial spheres. Specifically, we are concerned about how large banks have recently expanded their businesses into such fields as electric power production, oil refining and distribution, owning and operating of public assets such as ports and airports, and even uranium mining. [Isn’t that a national security issue?]”

Grayson, et. al. note, “Here are a few examples. Morgan Stanley imported 4 million barrels of oil and petroleum products into the United States in June, 2012. Goldman Sachs stores aluminum in vast warehouses in Detroit as well as serving as a commodities derivatives dealer. This ‘bank’ is also expanding into the ownership and operation of airports, toll roads, and ports. JP Morgan markets electricity in California.”

Grayson, et. al write, “According to legal scholar Saule Omarova, over the past five years, there has been a ‘quiet transformation of U.S. financial holding companies.’ These financial services companies have become global merchants that seek to extract rent from any commercial or financial business activity within their reach.  They have used legal authority in Graham-Leach-Bliley to subvert the ‘foundational principle of separation of banking from commerce’. This shift has many consequences for our economy, and for bank regulators. We wonder how the Federal Reserve is responding to this shift.” Read more.

ProPublica is tracking where taxpayer money has gone in the ongoing bailout of the financial system. The ProPublica database accounts for both the broader $700 billion stimulus bill and the separate bailout of Fannie Mae and Freddie Mac. According to their data: 927 banks received  $606B of which $366B has been returned. The banks revenues are $116B showing a total net to date of a minus $124B.

Following is the ProPublica list of Florida banks/mortgage servicers that were bailed out (those in RED failed to repay the government and resulted in a loss):

1st United Bancorp  
Alarion Financial Services  
Allstate Mortgage Loans & Investments, Inc.  
Bank United  
Bayview Loan Servicing, LLC  
Biscayne Bancshares, Inc.  
Capital International Financial, Inc.  
CenterState Banks of Florida, Inc.  
Central Florida Educators Federal Credit Union  
Coastal Banking Company  
Community Bancshares Of Mississippi, Inc. (Community Holding Company Of Florida, Inc.)  
Community Credit Union of Florida  
First Community Bank Corp of America  
First Federal Bank of Florida  
First Southern Bancorp  
Florida Bank Group, Inc.  
Florida Business BancGroup  
Florida Housing Finance Corporation  
FPB Bancorp  
GulfSouth Private Bank  
Gulfstream Bancshares  
Highlands Independent Bancshares  
Iberiabank  
IBM Southeast Employees’ Federal Credit Union  
Marine Bank & Trust Company  
Naples Bancorp  
Ocwen Financial Corporation, Inc.  
Pinnacle Bank Holding Company  
Premier Bank Holding Company  
Q Lending, Inc.  
Quantum Servicing Corporation  
Regent Bancorp  
Seacoast Banking Corp  
Seaside National Bank & Trust  
TIB Financial Corp  
U.S. Century Bank


For the full list of banking institution in the United States that received taxpayer bailouts click here.